


Use Your HSA/FSA Dollars Before You Lose Them: Connect Your Card to Stridekick

Pull up your last paystub. Somewhere between taxes and your 401(k), there might be a line that says FSA or HSA. That's money you set aside for health stuff. Before taxes. Every single paycheck.
Quick question: how much is in there right now?
Most people have no idea. The card is in a drawer. The login is... somewhere. And if it's an FSA, there's a deadline coming that nobody reminded you about. Meanwhile, you're paying for your health stack (the AG1 subscription, the Fitbit, the Bala bangles, the red light mask) with your regular, already-taxed paycheck. That's the problem we built this to fix.
First, what even is an HSA or FSA?
Both are accounts that let you pay for health expenses with money that skips income tax. Money goes in from your paycheck (and sometimes your employer), and you get a debit card to spend it.
- FSA (Flexible Spending Account): Set up through your employer. You pick an amount during open enrollment, up to $3,400 for 2026, and it comes out of each paycheck. The catch: most of it has to be spent by the end of your plan year.
- HSA (Health Savings Account): Paired with a high-deductible health plan. The money is yours for good. It rolls over every year and stays with you if you change jobs.
Why it matters: that money skipped taxes, so every dollar goes further. Depending on your tax bracket, paying with your HSA or FSA instead of your paycheck can save you roughly 20 to 40% on the exact same purchase.
Use it or lose it is real, and it isn't small
FSAs come with a catch. Money you don't spend by your plan's deadline goes back to your employer. Not to you.
And people lose a lot of it. In 2023, 47% of FSA holders forfeited money, an average of $422 each and roughly $4.5 billion total, according to Employee Benefit Research Institute data analyzed by Money. The year before, it topped $5 billion.
That's not because people are careless. It's because nobody shows them the number. The balance lives behind a login you never use, and the deadline sneaks up while you're busy living your life.
For most FSA plans, that deadline is December 31. Some employers let you carry up to $680 into next year, and others give you a grace period of up to two and a half months. But not every plan offers either, and no plan offers both. Not sure which you have? Assume December 31.
Have an HSA? Different rules, same blind spot
HSA money never expires. That's the good news.
The less-good news: if you don't know your balance, you're probably still paying for eligible stuff with your regular paycheck, money that's already been taxed, while your tax-free dollars sit untouched.
Your HSA will wait. Your paycheck won't stretch any further. Save your paycheck and optimize your spend on purchases you're already making.
Your health stack probably qualifies
The list of what qualifies is longer than most people think, and it goes well past the pharmacy aisle:
- Wearables and fitness trackers
- Strength, recovery, and posture gear
- Sleep tech and red light therapy
- Supplements and nutrition
Plenty of brands in the Stridekick HSA/FSA Shop are eligible, including the Apple Watch Series 11, InsideTracker, Forme posture wear, the BedJet sleep system, and Echelon strength gear.
If you're building your health stack, there's a good chance you're paying full price for things your health dollars could cover. Time to stop.
Introducing HSA/FSA card connection
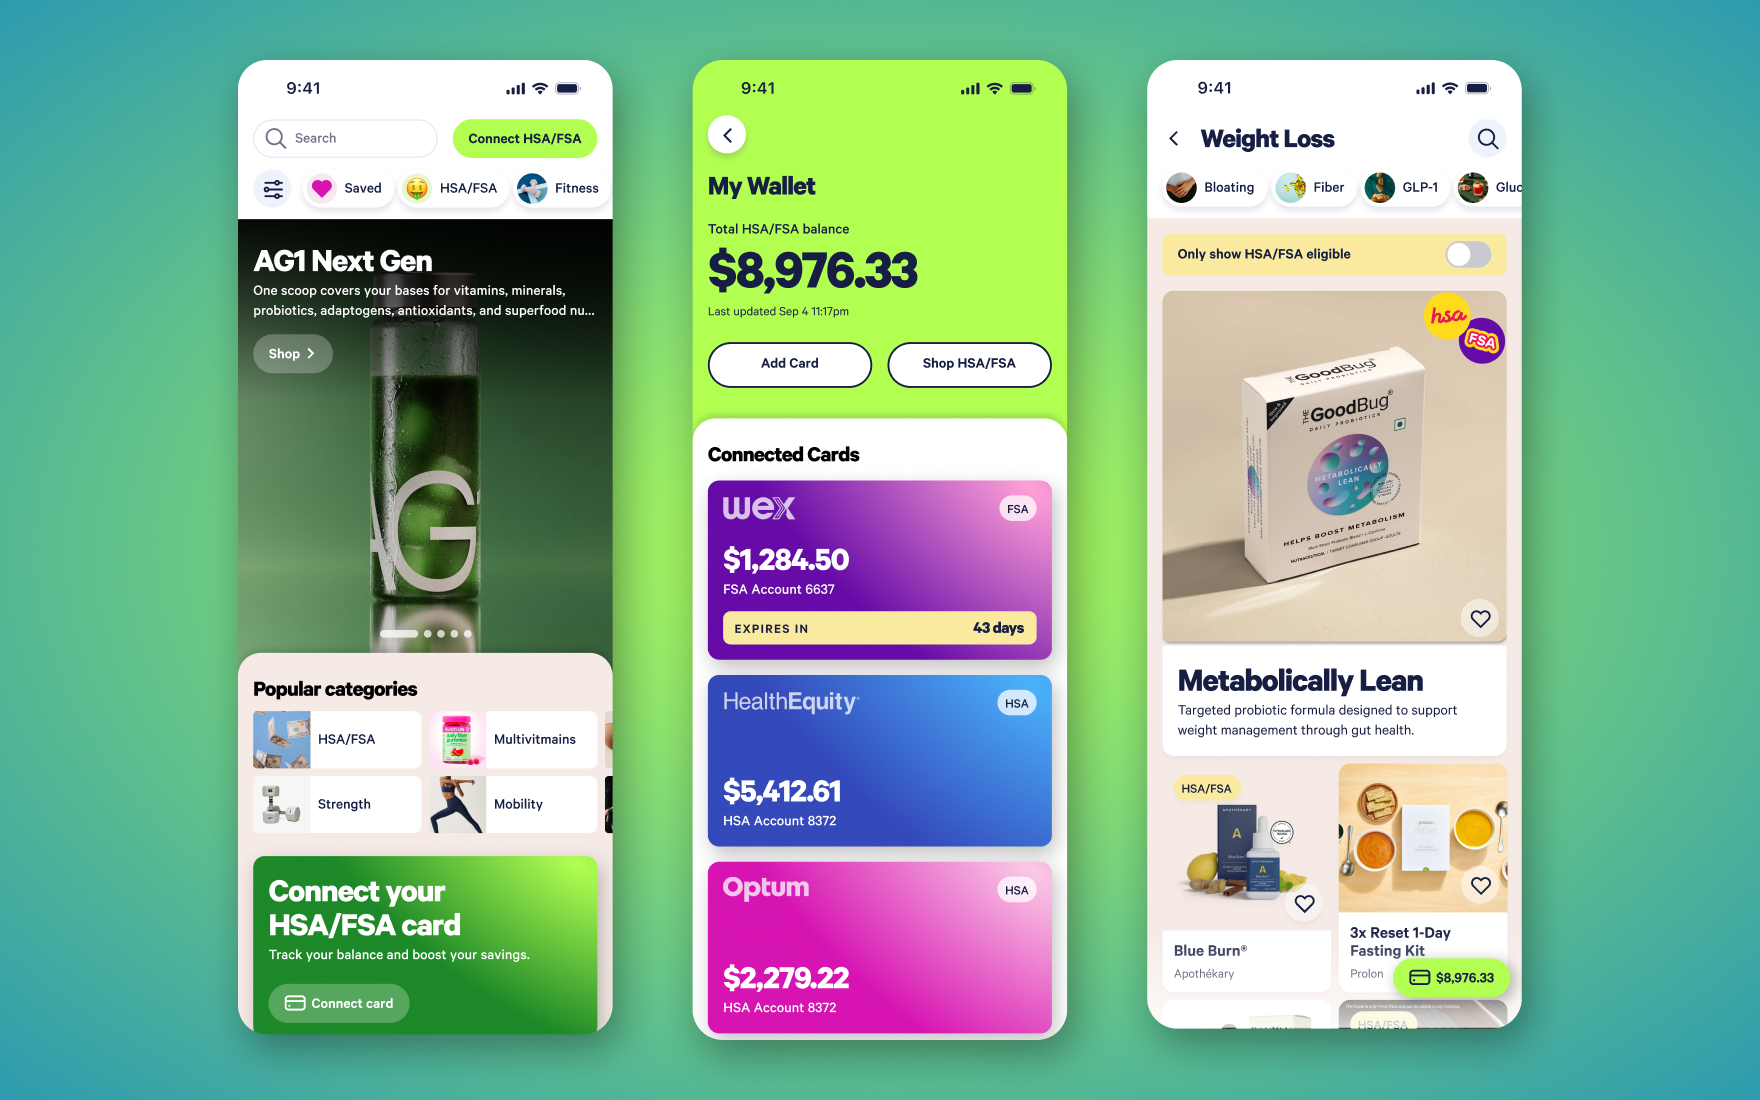
Step one to saving your paycheck: know how much you've got.
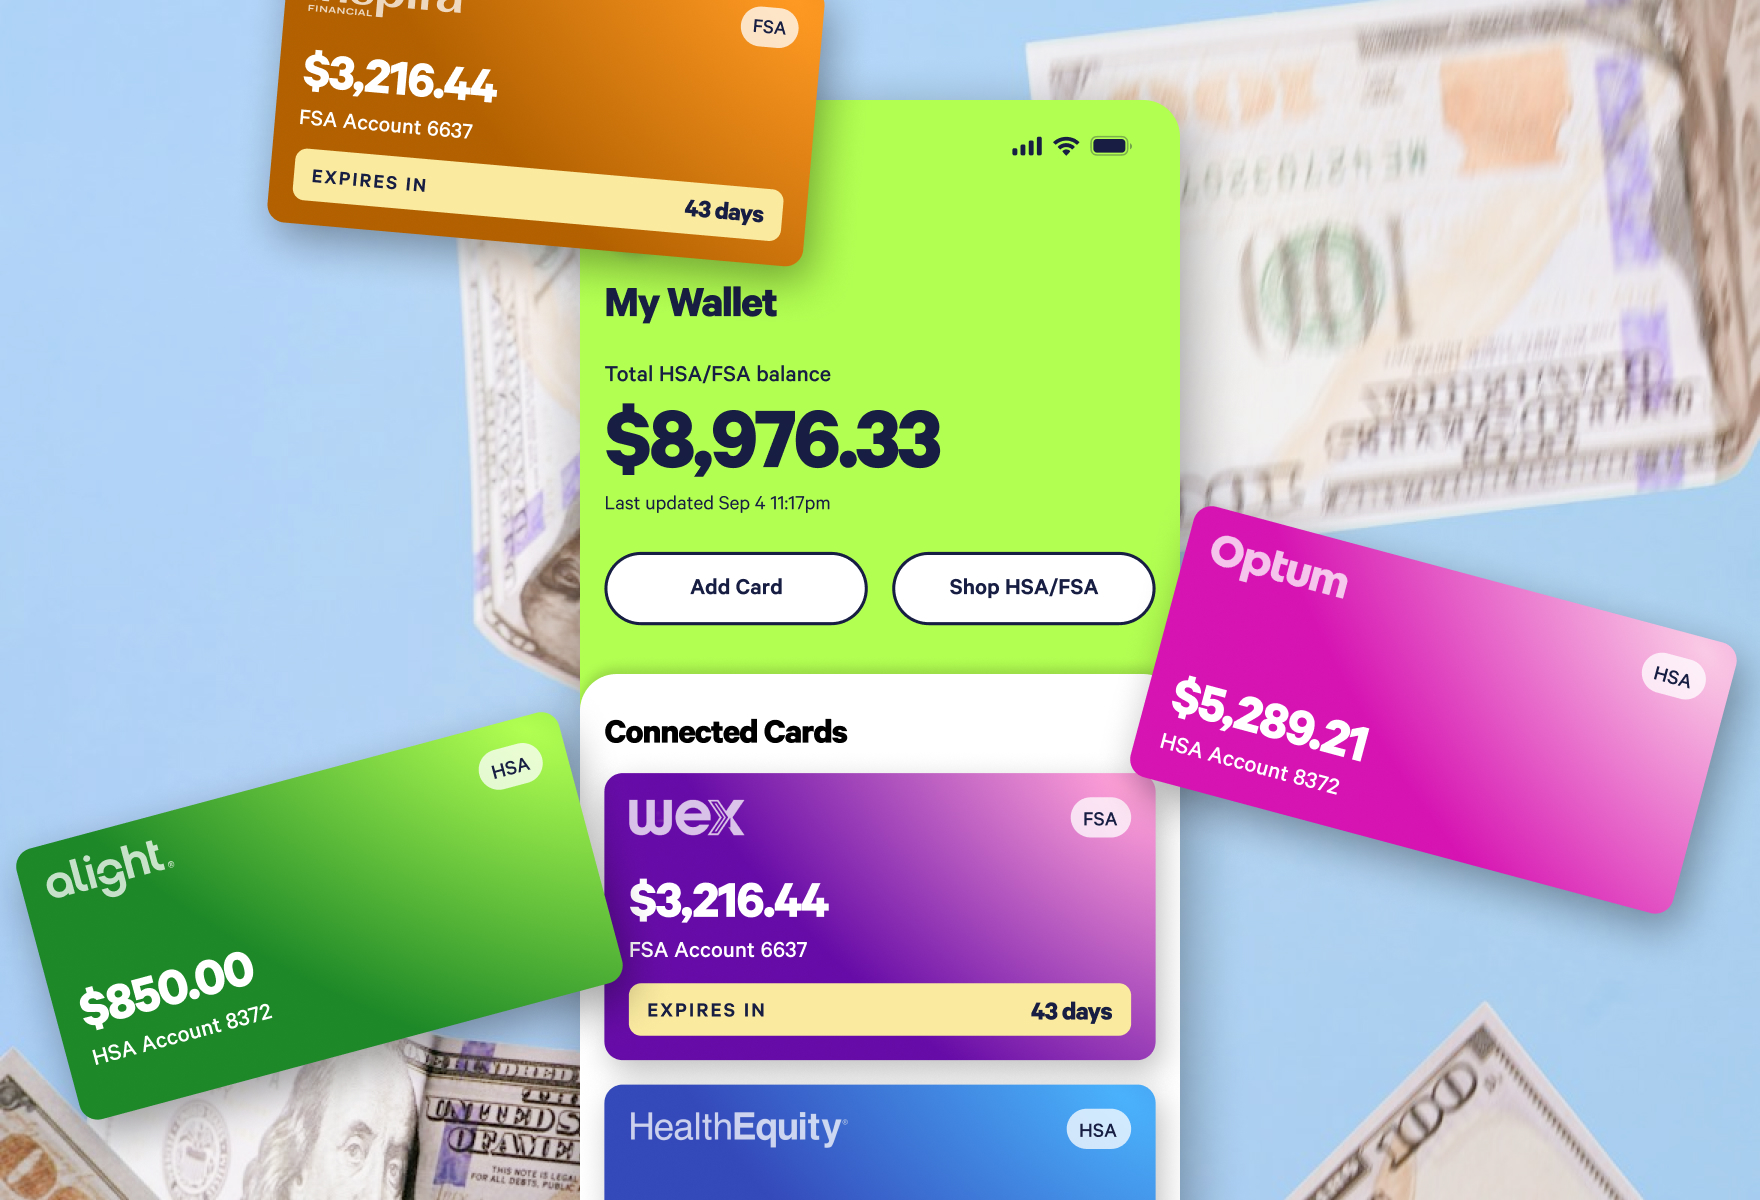
You can now connect your HSA or FSA card to Stridekick. It works with major benefit providers like Wex, HealthEquity, Optum, HSA Bank, Fidelity, Alight, BenefitWallet, Inspira Financial, PayFlex, and more. Once it's linked, your health dollars stop being a mystery.
[IMAGE PLACEHOLDER: Wallet page showing total balance across connected cards + last updated time. Figma: Wallet Page + Management]
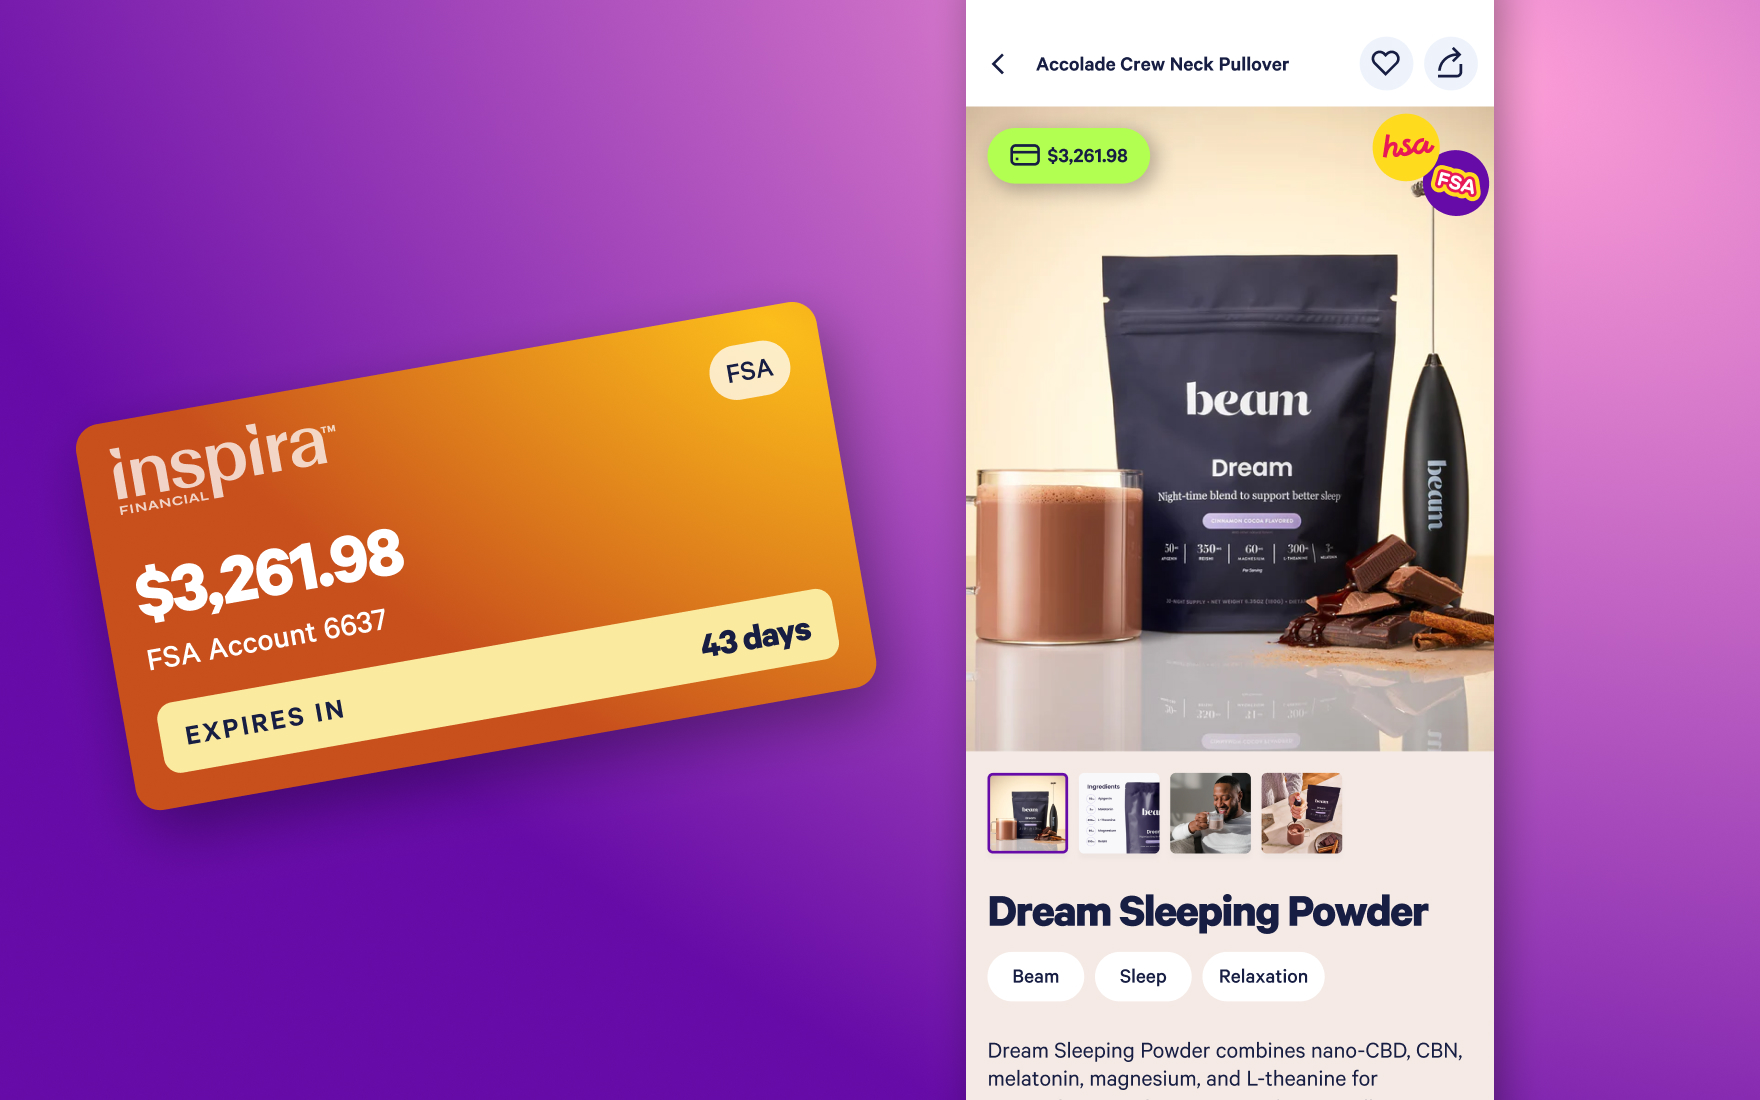
- Your balance, front and center. See your total across every connected card, plus when it last updated.
- Your FSA deadline, counted down. FSA cards show how much time is left before your funds expire, so December 31 never sneaks up on you.
- What you can actually buy. Browse HSA/FSA-eligible products in the Stridekick Shop, with your balance right there while you shop.
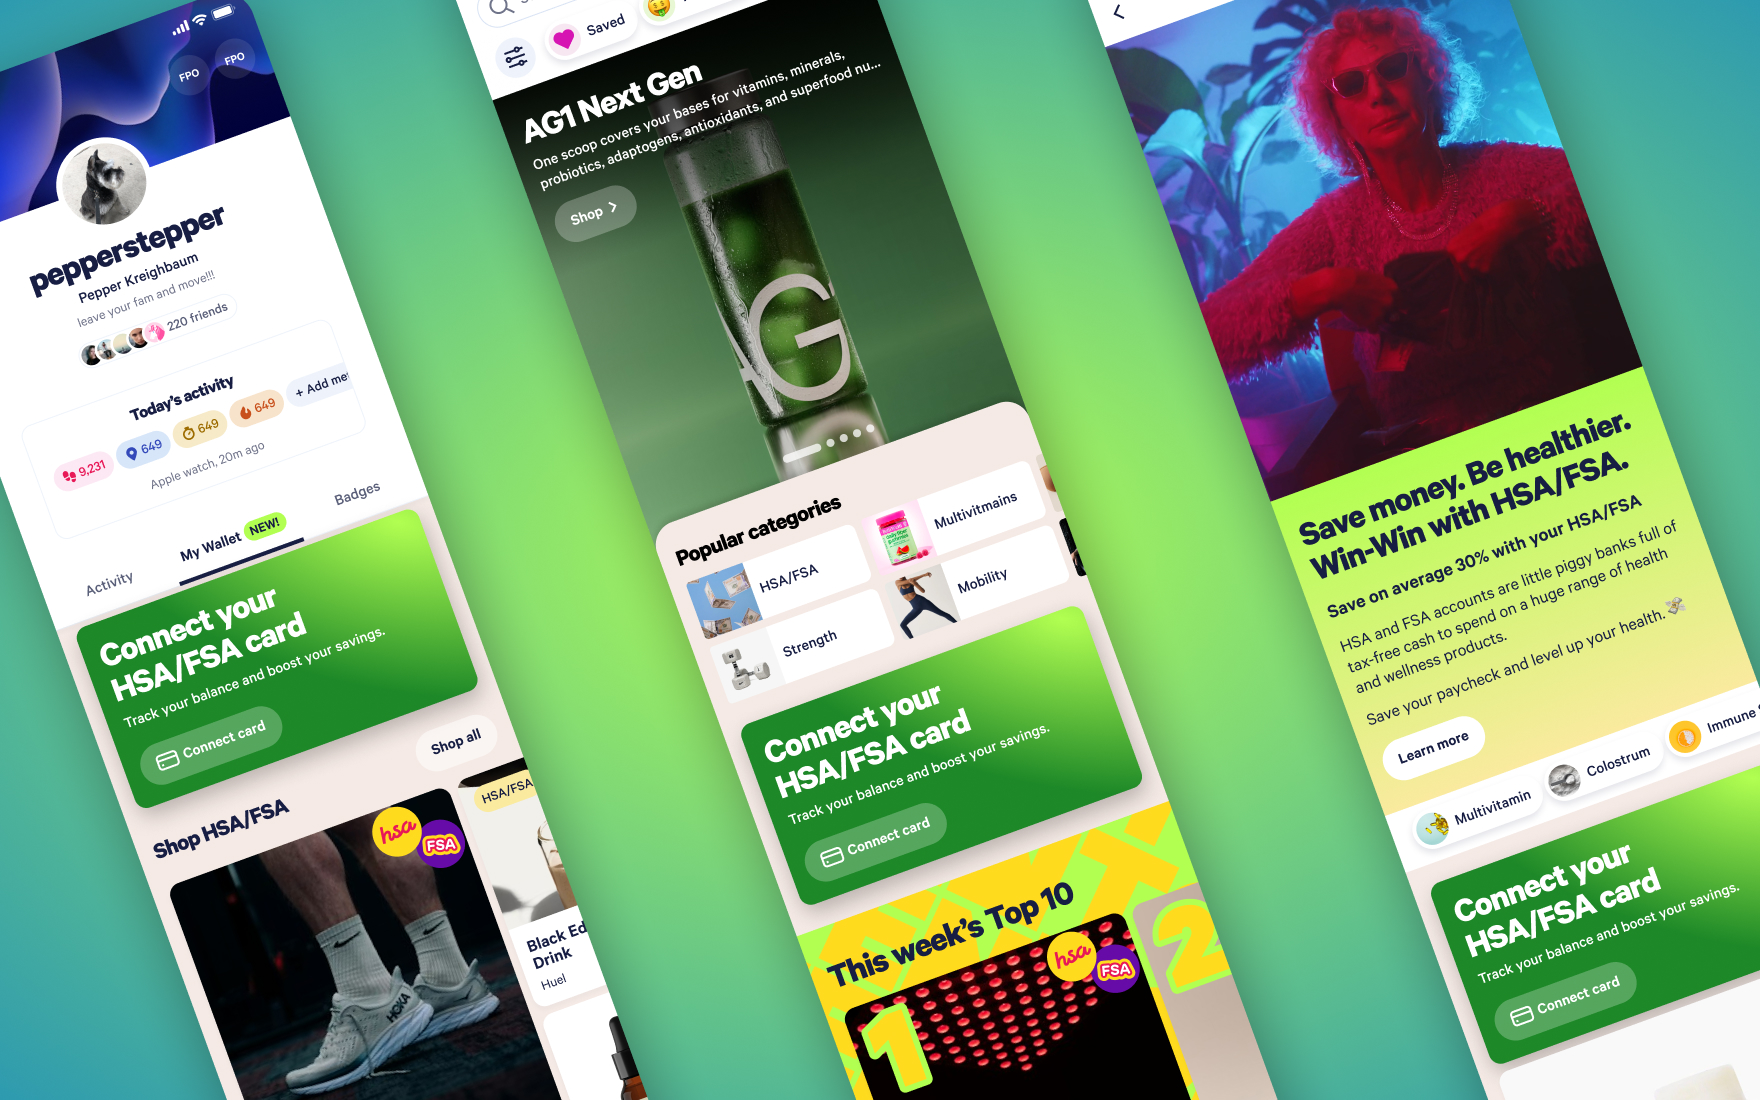
- All your cards in one wallet. Have more than one card? Connect them all. Tap your balance anywhere in the app to see each card, edit expiration dates, or disconnect anytime.
- Just for you. Your HSA/FSA tab is visible only to you. Your employer and challenge admins never see your balance or transactions, and we never see your full card number or benefits login. (Privacy Policy)
How it works
If you can log in to your benefits account, you can connect your card.
- Open the Shop tab and tap Connect HSA/FSA Card.
- Pick your card provider and sign in.
- Give it a moment to sync. Your balance shows up across the app.
That's it. Now you can shop knowing exactly what you have to spend, and when you need to spend it.
That money is yours. Don't let it go to waste.
You earned it. It came out of your paycheck. And if it's in an FSA, the clock is running. For most people, it runs out December 31.
Connect your card, see your number, and spend your health dollars on you.
HSA/FSA card connection is available now in the Stridekick app. Open the Shop and tap Connect HSA/FSA Card to get started.
Got questions? Visit our Help Center or email support@stridekick.com.
Eligibility rules vary by plan. Check with your HSA or FSA provider about what's covered and when your funds expire. Stridekick doesn't provide tax advice.
Related reading:
- How to Save an Average of 30% Using Your HSA or FSA With Truemed
- What’s a Letter of Medical Necessity? Everything You Need to Know About LMNs
- Reimbursing Yourself from Your HSA: A Step-by-Step Guide
- Stridekick Shop: A Curated Marketplace for Your Health & Wellness Needs
- Spend Your HSA/FSA Dollars on These Expert-Suggested Recovery Tools


